What it shows
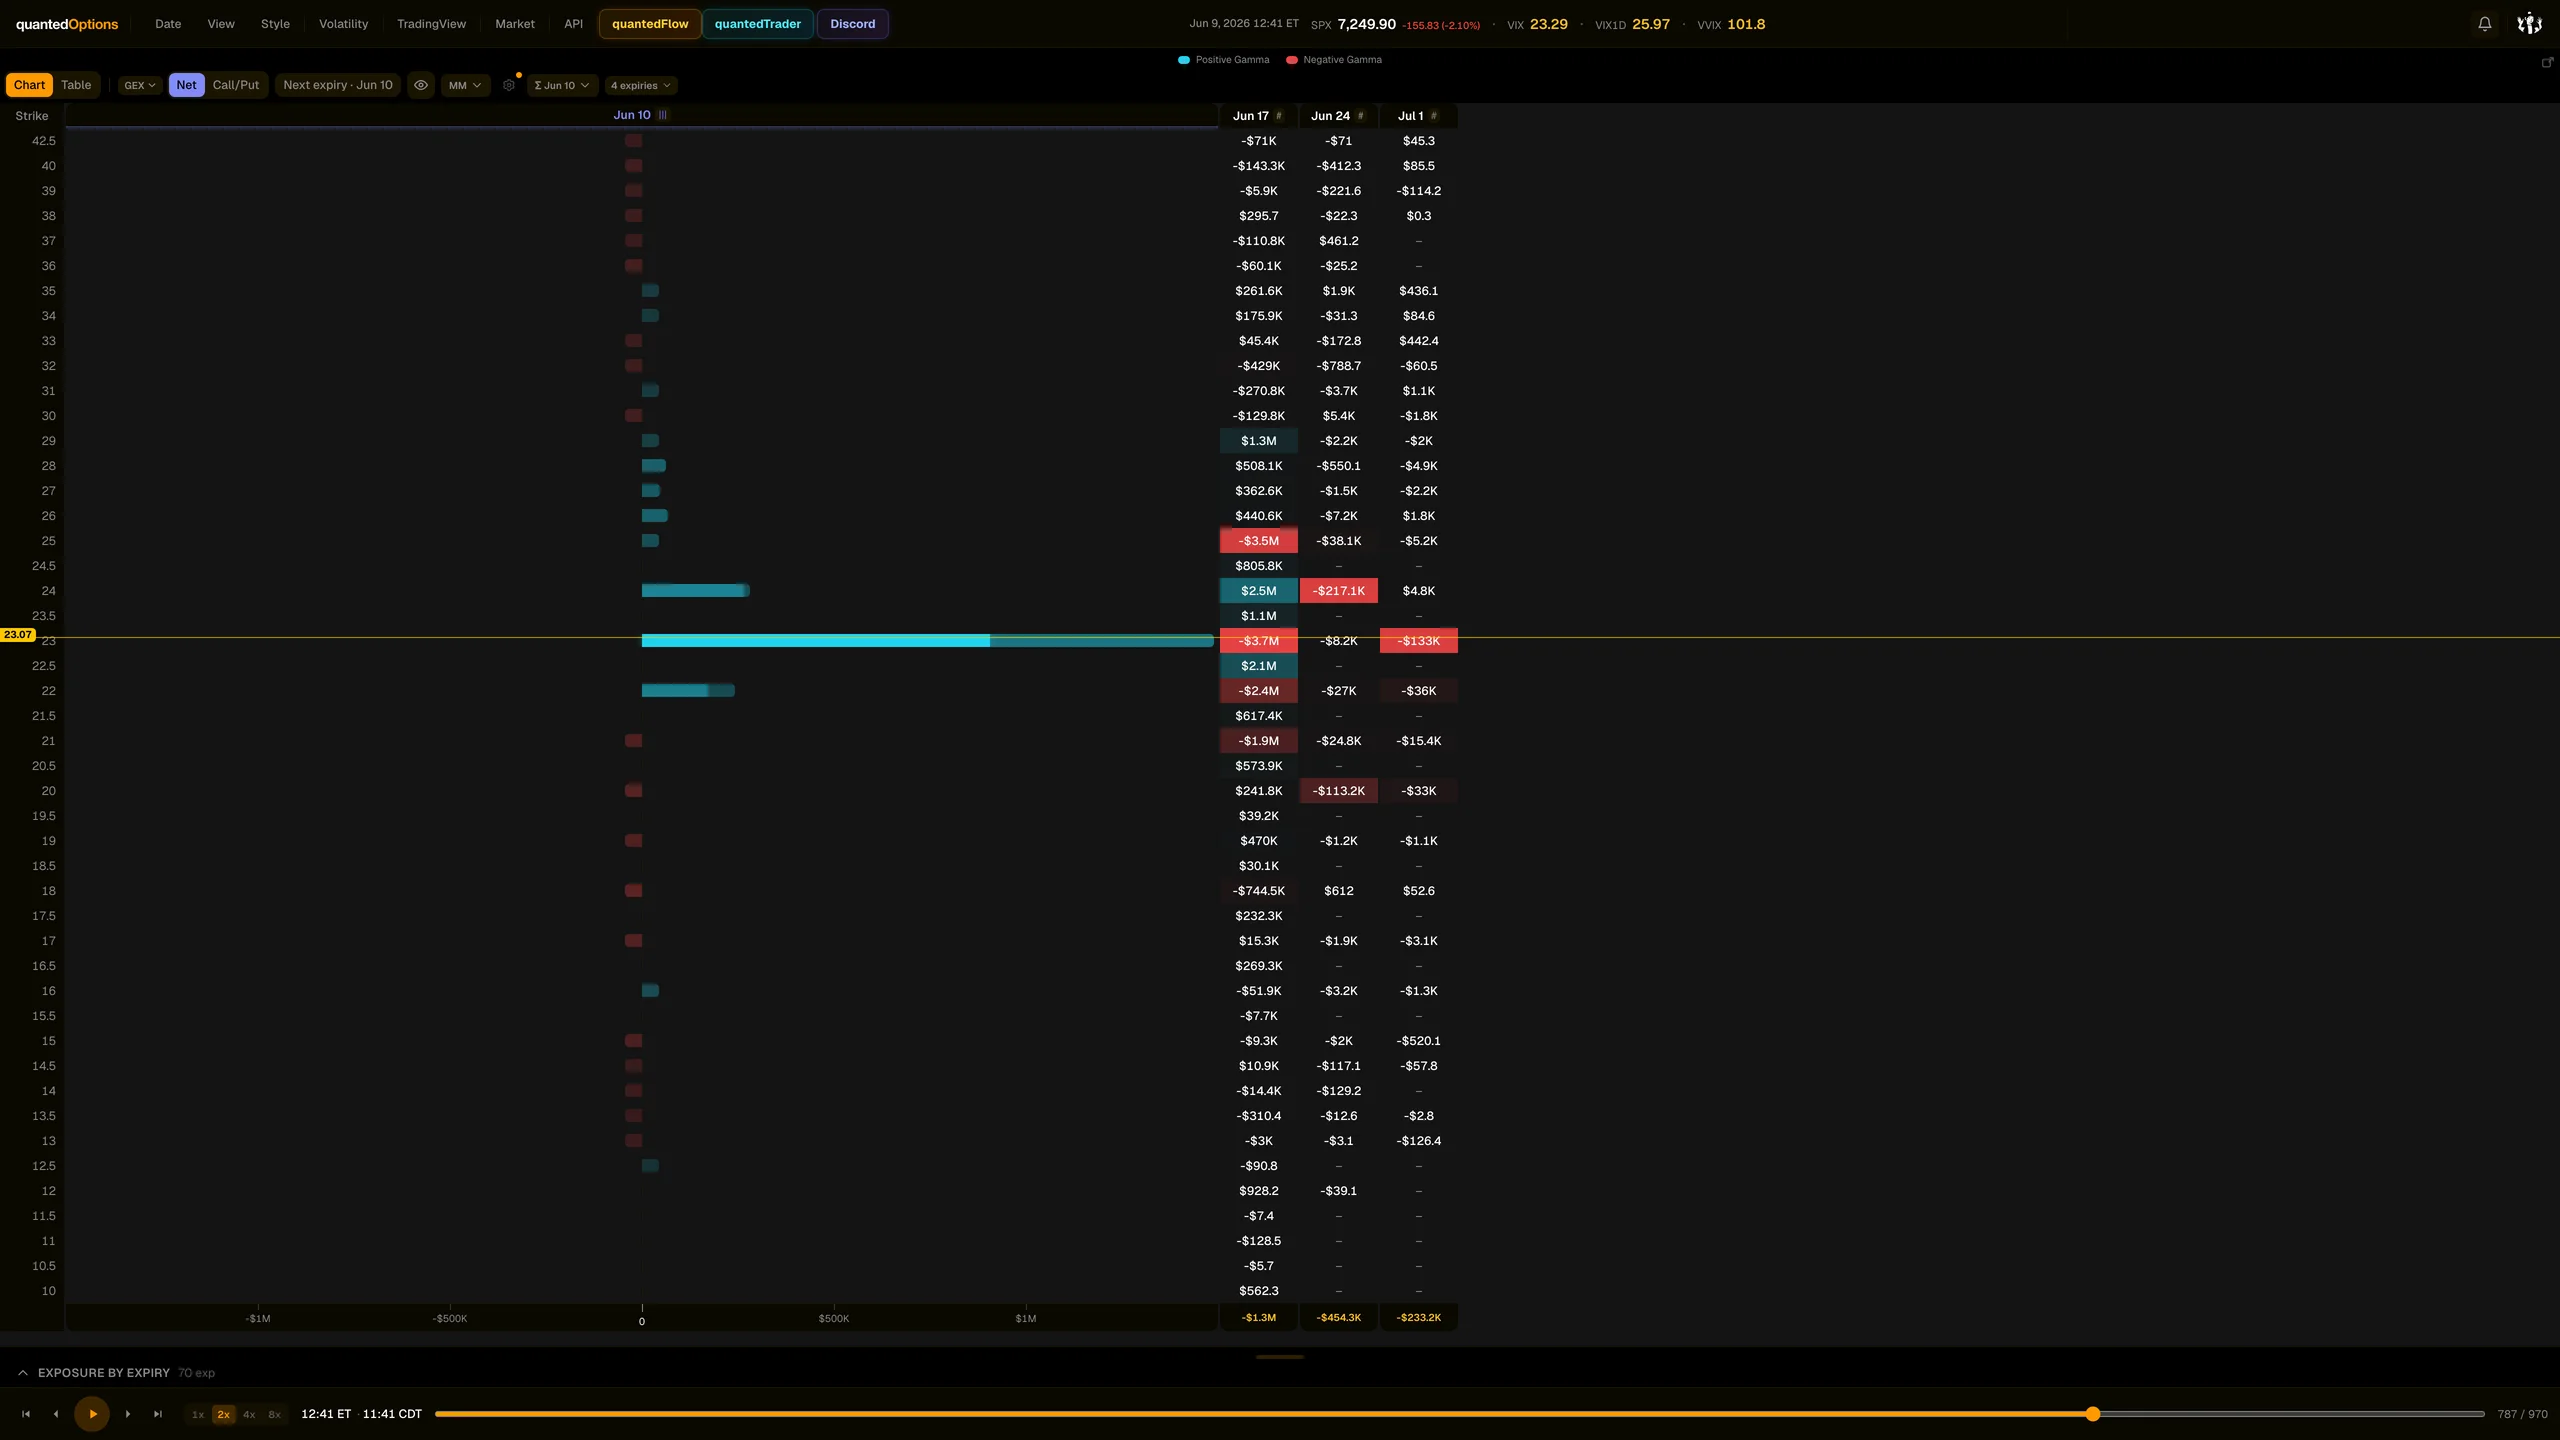
Market-maker exposure per VIX strike for the nearest live VIX expiry, with the same metrics and controls as the SPX ladder. The front ladder is labelled by its expiry date.
What it is built from
Each bar is the market maker's dollar exposure at that VIX strike. Built from licensed CBOE one-minute SPX and VIX data with market-maker positioning, recomputed every minute.
Reading
How to read it
- A large positive strike above VIX spot is where market makers are long VIX options; on 2026-06-09 VIX's high printed on that strike.
- The button that reads '0DTE only' on SPX reads 'Next expiry - <date>' here.
- On the Tuesday before a Wednesday expiry the front ladder is the contract that settles next morning.
Controls
What each control does
| Control | Options | What it changes |
|---|---|---|
| All Strike Profile controls | see SPX Strike Profile | Same as the SPX ladder. Range presets are +/-5, 10, 20, 50, All; steps 0.5, 1, 2, 5. |
Read it with
- Cumulative Net Delta (VIX mode) — VIX net delta beside the VIX ladder
- SPX Strike Profile — SPX and VIX side by side is the 'comparison' layout
Good to know
- VIX options settle in the morning (Wednesdays, or a displaced Tuesday). From 09:30 ET on that day the ladder moves to the next expiry.
- VIX exposures read in millions where SPX reads in billions: compare strikes within the VIX ladder.
A real session
See it happen
12:41 ET
VIX high 23.29; in the contract expiring next morning (2026-06-10), 23 was the largest positive gamma strike. SPX low printed one minute earlier.
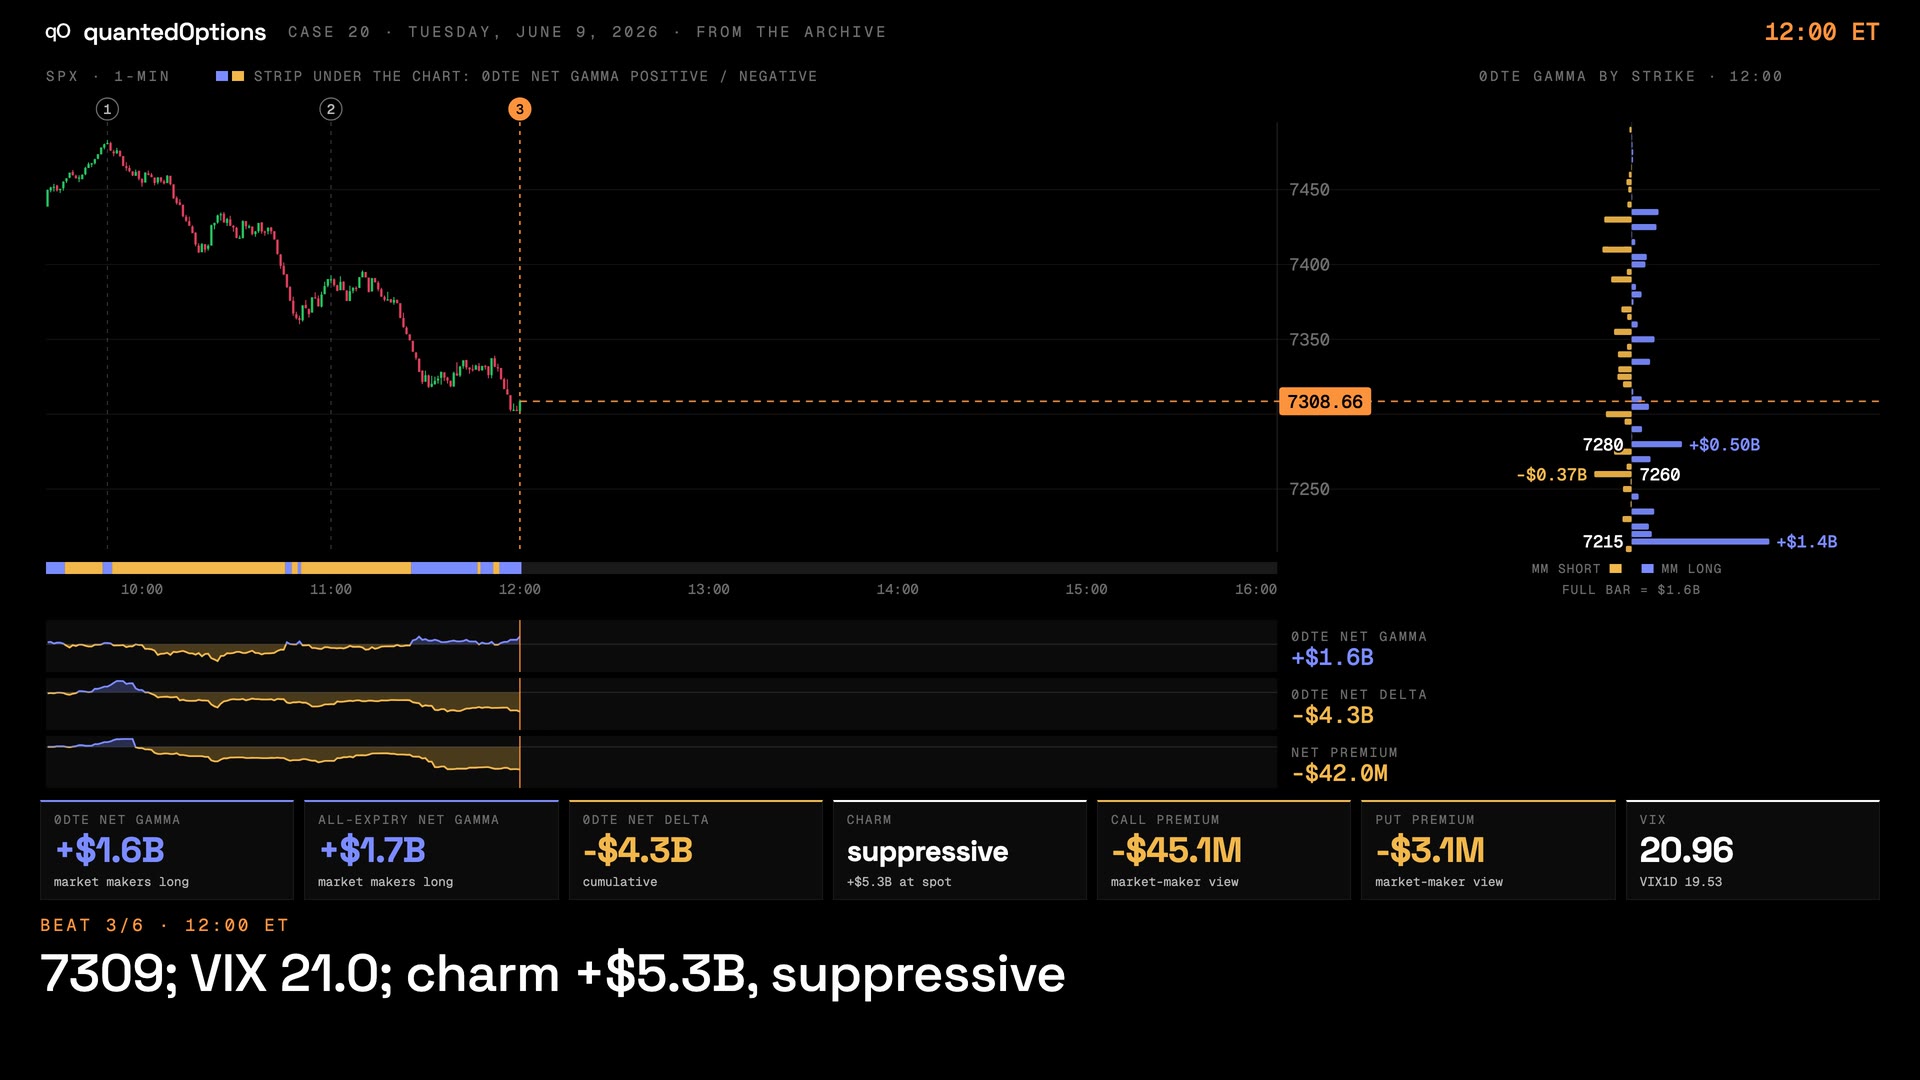
Case 20 · Jun 9, 2026
VIX ran to the expiring contract's largest strike and turned — and so did SPX
9 slides
The walk-through, slide by slide
Slide 1 / 9
From the product
Real frames
Shot off the live product, nothing redrawn. Click the right side of a frame for the next one, the left side to go back.
Product frame 1 / 2
These pages describe what the displays show and what the data did on the sessions shown. They are not trading advice, and a past session is not a forecast of a future one.